
Buying a completed resale home is simple: you pay most of the price at once. Buying a new launch is different. The building does not exist yet, so payments are spread across the construction period. Understanding that rhythm early helps you avoid cash-flow surprises years down the road.
Why Payments Are Staged
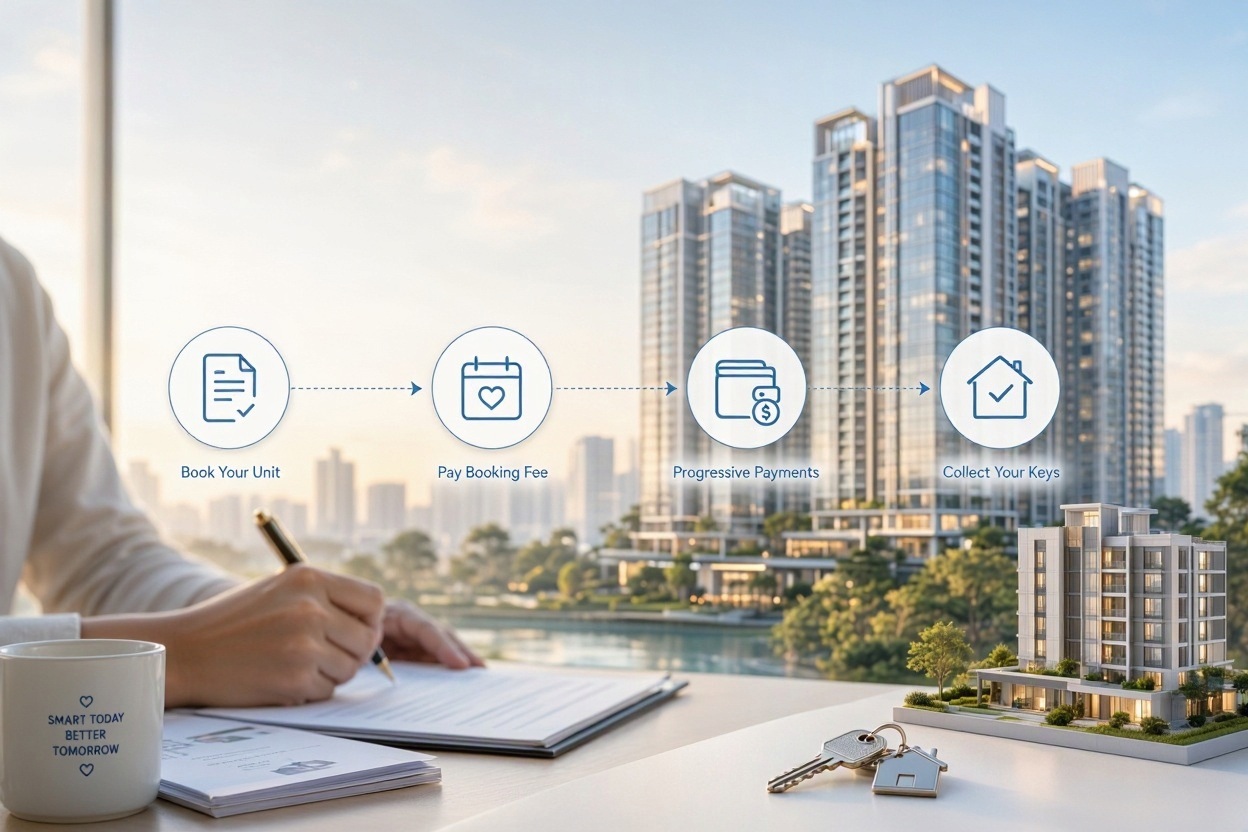
When you buy an uncompleted private home from a developer, you pay in instalments tied to construction milestones. This arrangement is known as the progressive payment scheme. Rather than paying everything on day one, you pay as the project reaches defined stages, such as the completion of the foundation or the framework. The balance falls due when the building is ready for occupation.
The practical benefit is that your loan is drawn down gradually. You pay interest only on the amount the bank has actually released, so early monthly repayments are usually lower than they would be on a fully drawn loan.
The Typical Sequence
Every project publishes its own schedule, so treat the following as a general outline rather than a rule.
Step 1: The booking stage. After viewing the showflat, you select a unit and pay an option fee to reserve it. This is a small percentage of the price, and cash is normally required.
Step 2: Exercising the option. Within a limited window, you sign the sale and purchase agreement and pay the initial downpayment. A portion of this must be paid in cash, while the remainder may be covered by CPF savings, subject to your eligibility.
Step 3: Construction-linked instalments. As each milestone is certified, the developer sends a payment request. These instalments can come from your bank loan, your CPF, or cash, depending on your arrangement.
Step 4: Completion. The largest remaining sum falls due around the Temporary Occupation Permit stage, with a final portion released after the Certificate of Statutory Completion.
Exact percentages and timing differ between developments, so request the official payment schedule from the sales team before you commit.
A Closer Look at Cash Flow
The real planning challenge is not the loan itself but the sequence of cash needs. Early on, you need enough liquid funds for the option fee and the cash portion of the downpayment. Later, your monthly outgoings will rise as more of the loan is drawn. Many buyers are also paying rent or an existing mortgage at the same time, so it is wise to model overlapping costs.
Here are a few questions to work through before you sign:
- How much cash, separate from CPF, can I commit upfront?
- Will I be paying rent or servicing another loan during construction?
- What happens to my budget if interest rates rise?
- Is there a buffer for stamp duties and legal fees?
Using Real Projects as Practice
You can test your thinking on projects that have not launched yet. Chencharu Central Residences is a good case study. The mixed-use development in Yishun is expected to hold up to about 875 homes, and its website already offers a payment scheme page and a progressive payment calculator. Launch timing and pricing are still to be announced, but running sample figures now shows how different price points would change your staged payments.
Remember that a large project can take several years to complete, which means a longer period of staged payments. Longer timelines give you more time to save, but they also extend your exposure to changing interest rates and personal circumstances.
Executive Condominiums Can Differ
Executive condominiums follow their own conditions. Some developers offer alternative arrangements, such as deferred payment, where a larger share of the price is settled later in the construction timeline. Whether a particular project does so must be confirmed with the developer. If you are eligible for an EC, compare the payment terms carefully, because the structure can affect how much cash you need in the early years.
Fablewoode Residences, a planned low-rise executive condominium on Sembawang Road, offers both a progressive payment calculator and a deferred payment calculator on its website. Its official name, launch date and pricing are yet to be confirmed, but the tools are handy for comparing how different payment structures might feel month to month.
Final Checks Before You Commit
- Read the sale and purchase agreement fully, ideally with a lawyer.
- Ask for the full payment schedule in writing.
- Confirm your loan eligibility with a bank before the option fee.
- Keep an emergency reserve beyond the amounts due.
- Verify current stamp duty and loan rules with IRAS and MAS.
A new launch rewards patience and preparation. Buyers who map out their payment timeline in advance tend to feel far more in control when each instalment arrives.