
For generations, families across Telangana have treated gold as a financial safety net, something that can be pledged in a difficult month and reclaimed once things improve. A farmer needing funds before a harvest, a small shopkeeper managing cash flow, or a parent covering an urgent medical bill may all turn to a gold loan. When the Today Gold Rate rises, the amount that can be borrowed against the same ornaments rises with it, and this is why loan enquiries tend to follow price trends closely. Residents who follow Gold Rate Today Hyderabad often realise that their jewellery box holds more borrowing power than they imagined. Yet a loan is still a loan, and the ease of getting one should never replace careful thought. This article explains how gold loans work, what to check before signing, and how to borrow responsibly.
How Gold Loans Work
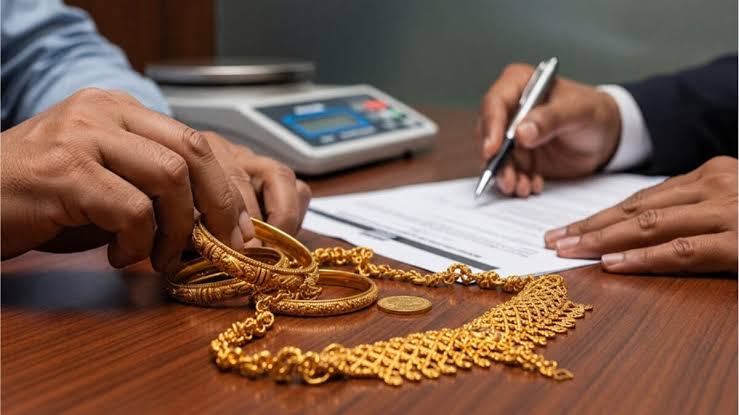
A gold loan is a secured form of borrowing where a borrower pledges a certain amount of gold ornaments, coins or similar items of value with a lender against whom a cash loan is sanctioned. As the lender has the security of valuable goods, the loan process is fast and involves minimal red tape as compared to an unsecured personal loan. The lender evaluates the purity of the gold, deducts any loss due to the weight of associated stones and calculates the amount on the basis of the current market price. This estimated amount provides an indication of the loan value that may be sanctioned, with a certain percentage of this value offered as the loan amount. The ornaments are kept in the vault of the lender till the time the loan is repaid. It is crucial to understand the repayment options available. While some may allow for monthly interest payments with principal payable at the end of the tenure, others may offer the option of regular instalments or a bullet payment of the entire loan amount upon maturity. Understanding which repayment method is more suited to one’s cash flow is a crucial first step.
Loan to Value and Interest Rates
Certain factors become important while choosing the right loan scheme. Two crucial aspects are the loan-to-value ratio and the applicable rate of interest. The loan-to-value provides an indication of the portion of the calculated value that will be financed as a loan. While there are regulatory caps on this ratio to safeguard the interests of both parties against sharp declines in gold prices and limit risks, the lending institution operates within this range. While a lower percentage would imply a smaller loan amount, it does provide safety against price fluctuations. The interest rate charged on a gold loan will differ from lender to lender and may also depend on the sanctioned loan amount, tenure and repayment choice made. It is important to request a detailed view of the applicable charges, including those applicable for early closure, valuation and processing. It is prudent to obtain the cost sheet in writing for the option chosen and calculate the effective cost of borrowing under different scenarios to understand the likely additional burden of charges. Comparing across two or more lenders and not just the first attractive offer will save significantly on the cost of the loan over its life.
The choice between a bank and a non-bank lender
Gold loans in Telangana are available from public sector banks, private banks, cooperative banks as well as non-bank finance companies that specialise in providing such loans. While banks offer comparatively lower rates of interest and assurance of a reputed institution, the processing time may be slightly longer and require additional documentation. Non-bank lenders tend to offer speed and convenience and have an extensive branch network with longer service hours, which may be vital in an emergency. Cooperative institutions may offer competitive rates to their members and have a presence in local markets. Irrespective of the choice of the lending institution, it is important to ensure that the entity is authorised by the relevant financial regulatory authority. In addition to asking questions about the storage and insurance of the pledged gold, one must also enquire about the valuation methodology and the dispute resolution mechanism in case of differences in the valuation of gold. It is essential to read the fine print of the auction clause as this becomes applicable in case of default and explains the procedure for giving notice for auction. A responsible lender will patiently explain the clauses, and any undue haste in pushing the borrower to sign the agreement should raise a warning signal.
Repayment discipline and managing risks
The biggest risk in a gold loan is the temptation to treat the loan as a readily available source of cash, which makes default almost inevitable. Defaulting on repayments will mean auction of the pledged gold, and the family may lose a valuable possession that could have been passed on as a family heirloom. It is essential to only borrow what is required and only when there is an immediate need and a realistic repayment plan in place. It is important to keep track of the due dates for instalments and consider making regular interest payments till the due date of the principal repayment if the option is available, as the accumulated interest could also prove to be a strain at the time of maturity. If the cash flow situation permits, one should think of prepaying a portion of the outstanding loan amount, if no penalty is applicable for the same. Keeping copies of all relevant bills and the original loan agreement, along with verifying the contents of the ornaments upon return of the same, are other vital steps in a gold loan arrangement. Lastly, one must remember that gold prices are volatile and one should not assume that prices will always rise. It is important to exercise prudence while borrowing to let gold serve its true purpose of being a family possession rather than becoming a burden to the family.
A gold loan can be an extremely useful financial instrument if managed wisely. Understanding the fine print, weighing the offers of different lenders and exercising caution while borrowing against gold possessions can help families turn to gold in times of emergency without risking their gold ornaments.